Search Results for: incentives to invest

Investing in telecom

In 2022, Canadian carriers were investing in telecom infrastructure at an accelerated pace.

That is one of the findings of a new report prepared by PwC. “Connecting Canadians through resilient networks: The impact of the telecom sector in 2022 and beyond” [pdf, 4.5MB] found that Canada’s six largest telecom companies invested $13.3 billion in capital expenditures in 2022. Over the past five years, the Canadian telecom sector has invested an annual average of $12.1 billion in capital on network infrastructure, expanding, enhancing, and strengthening Canada’s wireless and broadband networks. This represents approximately 18.6% of average revenues, which is 30% higher than the 14.2% average across peer telecom carriers in the US, Japan, Australia, and Europe. Canada’s elevated capital intensity is similar to what was found in another recent study.

As I have reported in my monthly analysis of Statistics Canada data, PwC confirmed that for the year ending September 2023, cellular and internet access service prices declined by 17.2% and 7.8%, respectively, while the Consumer Price Index for All-Items increased by 3.8% over the same period.

PwC says the telecom sector contributed nearly $77B to Canada’s GDP, and supported nearly three quarters of a million Canadian jobs in 2022. It estimates that by 2035, the telecom sector’s delivery of enhanced connectivity, including 5G, has the potential to contribute an additional $112B to Canada’s GDP.

Key findings:

  • Direct GDP contribution and jobs supported by the telecommunications sector in 2022 is estimated to be $76.7 billion and 724,000 jobs (versus $74.9 billion (+2.4%) and 650,000 jobs in 2021 (+11.3%)*);
  • Enhanced connectivity, including 5G, has the potential to contribute an additional $112 billion to Canada’s GDP by 2035
  • Telecom’s direct GDP contribution includes $24.7 billion from the sector’s value chain and up to $52 billion in direct impact from increased sales and other outputs from other Canadian industries through the incremental addition of additional wireless and broadband connections;
  • The six largest Canadian telecommunications operators invested $13.3 billion in capital expenditures in 2022 to continue expanding and enhancing their wireless and broadband internet networks;
  • Over the past five years, Canada’s telecom sector has invested an average of $12.1 billion annually on network expansion and enhancements. This represents a capital intensity that is approximately 18.6% of average revenues. That is higher than the 14.2% average across peer telecom operators in the US, Japan, Australia and Europe;
  • Continued investments in Canada’s telecom sector connect more Canadians to advanced wireless and broadband internet networks, supporting increased data consumption, powering the digital economy, and providing a range of other social and environmental benefits:
    • 99.7% of Canadians had access to mobile network coverage where they lived or conducted business in 2021, including 87.8% who had access to 5G connectivity;
    • 93.5% of households had access to high-speed internet with speeds meeting the CRTC’s 50/10 Mbps targets in 2022. The CRTC estimates that services providers are on track to meet its broadband targets for 98% of households to have access to 50/10 Mbps unlimited services in 2026, and 100% by 2030;
  • The price of telecommunications in Canada has fallen over the past year, with cellular service prices down 17.2% and internet access service prices down 7.8% between September 2022 and September 2023, while the all-items Consumer Price Index increased by 3.8%;
  • The telecommunications sector has already suffered millions of dollars in damages to Canadian network infrastructure as a result of severe weather events and other natural disasters. Canadian service providers are investing in building resilient networks to manage future risks.

The bottom line? Maintaining incentives for investing in telecom infrastructure is key to Canadian economic growth.

Sustainable competition and continued investment

This decision helps to promote access to affordable telecommunications services for Canadians and to foster sustainable competition and continued investment.

That was how the CRTC summarized its decision last night on final offer arbitration between Bell Mobility and Quebecor for wholesale mobile virtual network operator (MVNO) access rates.

The decision was notable for a few reasons:

  • A focus on creating and maintaining incentives for investment;
  • Fostering “sustainable competition”, which has historically been CRTC and Competition Bureau language for “facilities-based competition”;
  • Clarifying that the wholesale framework is not intended to guarantee profitability for wholesale-based service providers;
  • The CRTC explicitly discounted the usefulness of comparisons to European rates;
  • Recognition that average network costs don’t support investment in suburban and rural infrastructure.

The Bell – Quebecor decision should be read in the context of a similar arbitration between Rogers and Quebecor released by the CRTC nearly two months ago. In the earlier instance, the CRTC required Rogers to offer a wholesale service at rates acknowledged to be below Rogers’ costs. The CRTC said Rogers’ shortfall could be made up “through other telecommunications services”. The Rogers decision has been appealed to the courts because of the precedent-setting nature of wholesale rates being set below costs.

This week, the CRTC selected Bell Mobility’s offer.

The Commission clearly accepted the concern that wholesale rates impact the incentives for investment by both parties.

  1. Nevertheless, the Commission considers that Bell Mobility has raised a valid concern regarding the long-term impact of artificially low wholesale rates on the policy objective of fostering network investments, which is particularly relevant in suburban and rural areas. While lower retail prices backed by lower wholesale rates are desirable, as discussed earlier, these different interests must be balanced with the wholesale MVNO access provider’s incentives for continued network investment. Accordingly, the Commission is of the view that Bell Mobility’s offer best strikes the balance of maintaining both parties’ incentives to invest.

The CRTC said “the MVNO access framework is not intended to guarantee a risk-free profit margin for [Quebecor’s] MVNO operations, and QMI’s ability to compete should not be assessed by looking at only the profitability of specific plans, but rather by looking at all of the wireless plans it offers.” While the CRTC wants to see lower-priced plans, it also needed to consider the potential negative consequences of lower rates on sustainable competition, and incentives for investment.

The Commission referred to the controversial cross subsidization aspect of the Rogers – Quebecor arbitration decision in this Bell – Quebecor determination, saying “that it does not necessarily have to ensure that costs are recouped over the short term for a rate to be considered just and reasonable, fair compensation for the wholesale MVNO access provider is still an important consideration in evaluating offers”.

Quebecor had asked the CRTC to compare Canadian wholesale rates to those found in Europe. The CRTC clearly stated European wholesale roaming rate structures “have very limited comparative value given the different contexts in which European and Canadian carriers operate, resulting in different cost structures.” Many Canadians have fixated on international comparisons that have such “limited comparative value” precisely because of the “different contexts in which European and Canadian carriers operate”. It was somewhat encouraging to see the CRTC explicitly discount such comparisons.

Finally, the CRTC seems to have given weight to the argument that wholesale-based service providers have uneconomic arbitrage opportunities when average rates are applied for urban, rural and suburban traffic. Such rate structures create incentives to build urban facilities but create a disincentive for investment in suburban and rural areas. “Bell Mobility submitted that, on average, a rural cell site costs more to build, while serving less data volume, than an urban one, resulting in higher costs per GB.” As Scotiabank observed in a research note this morning, Quebecor’s favourable MVNO deal with Rogers will result in Bell’s network being used only in areas where Rogers isn’t as strong. This would result in a disproportionate level of wholesale traffic running on rural and suburban while leading to disincentives for either party to invest.

Fostering sustainable competition and continued incentives for investment are clear themes of this wholesale wireless rate decision. To what extent does it provide clues for the way the CRTC will approach revisions to the wireline wholesale framework?

Climate for investment looking cloudy

Canada’s policy environment is leading to the wrong climate for investment.

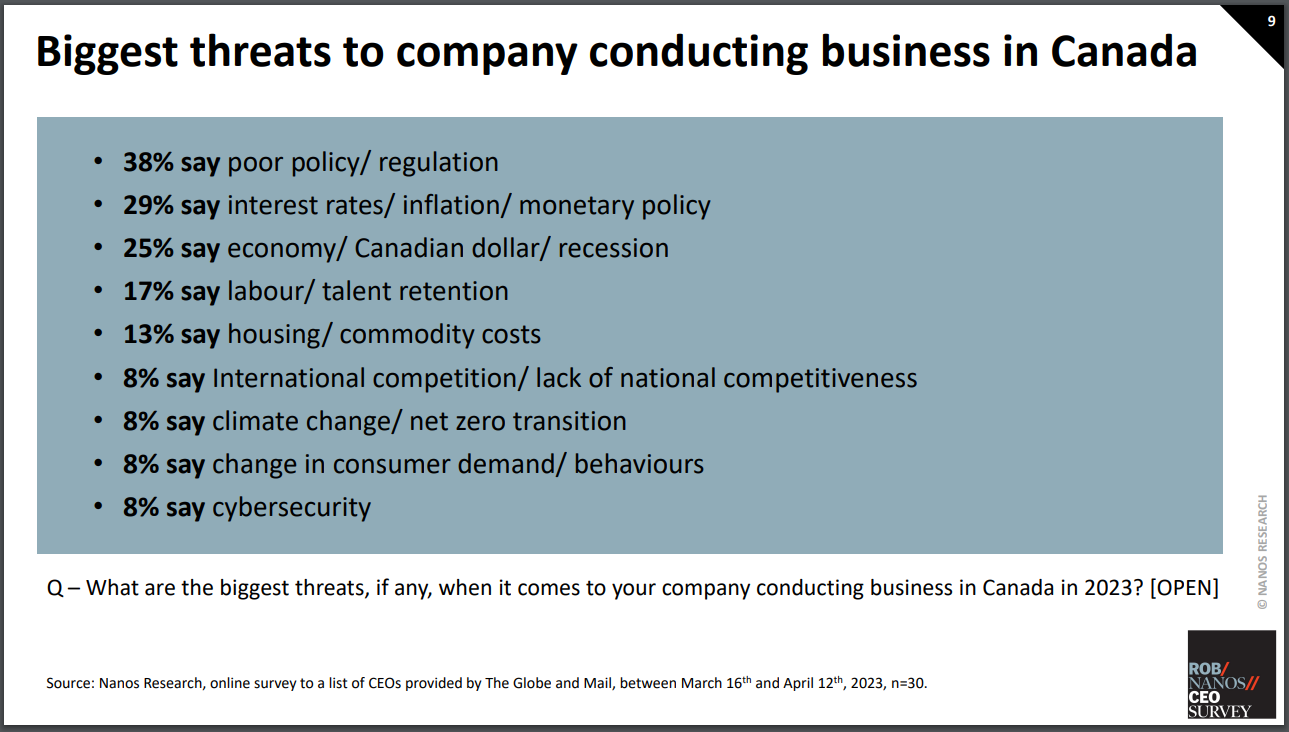
That is one of the key take-aways from a recent survey of leading business leaders published by the Globe and Mail. The survey [pdf, 5.2MB] included chief executives from a wide range of companies and business sectors, representing businesses with annual revenues ranging from $10M to more than $10B. Two thirds of the respondents represented companies with annual revenues over $1B.

The survey’s headline highlights nine out of ten participating CEOs in Canada see cybersecurity as a threat for their business; 70% say it’s a major threat. Still, Canada being on the wrong track for investment is one of the 4 key findings. “Over six in ten participating CEOs in Canada see Canada as being on the wrong track when it comes to being a place for businesses to invest (62%). When asked the reason for their views, participating CEOs most often said taxes and high costs (22%), poor leadership, regulators, and red tape or lack of clarity (22%), and incentives for business being weaker than other countries which does not create appealing environment for investment (17%).”

Further, when asked an open ended question “What are the biggest threats, if any, when it comes to your company conducting business in Canada in 2023”, 38% replied poor policy / regulation. It was the number one threat identified, by a nine point margin.

The regulatory and policy impact on the climate for investment is a key theme in the CRTC’s review of mandated wholesale access to fibre facilities. In its notice of consultation, the CRTC appears to trivialize the risk to further fibre investment by carriers, since fibre access networks “now cover most of their serving territories”. That stands in stark contrast to a recent statement by Bell Canada’s CEO that “There are still 4-5 million locations within our footprint without access to fibre.”

The regulator should know that broadband expansion business cases are examined on a project-by-project basis. After all, the CRTC administers its own subsidy fund to top up the shortfall in a limited number of rural broadband expansion projects. Policy makers must recognize that existing fibre is somewhat irrelevant to the millions of Canadian households that currently don’t have fibre access.

The economics associated with fibre expansion projects should be pretty simple to understand. I have written about broadband business cases numerous times. The incremental cashflows over time have to offset the upfront and ongoing costs associated with the project. If there is a shortfall, the project doesn’t get approved. If the economics don’t work, the private sector won’t invest in the project.

Cutting investment and cutting jobs aren’t threats; these are logical (and predictable) consequences of regulatory and government policy.

This week, we have seen stories about such consequences at TELUS and at Bell.

Will CRTC’s continued intervention in the marketplace drive an increased requirement for government funding for fibre in areas that would have otherwise had a business case for private sector investment?

Recognizing investment in Canadian networks

The public interest for telecommunications is multi-dimensional. Although some lobbyists seem to focus solely on lower prices, government policy needs to balance other factors, like investment in increased coverage, new technology and services, and quality.

Last Thursday, when Minister François-Philippe Champagne announced a new policy direction, there were 3 “associated links” in the press release:

Much of the focus of media coverage was on the proposed Policy Direction as well as the disposition of the wholesale rates appeal:

We recognize the important balance that must be achieved between the need to invest in our networks and the need to promote continued competition and affordability. The wholesale rates decision made by the CRTC in 2021 is an attempt to correct errors made in 2019, and it makes permanent the rates that have been in force since 2016. The decision provides stability, and the government has determined that it will not alter this decision.

My initial impressions were captured in a blog post, “A new direction for Canadian telecom”.

I noticed that many of the news articles cited language that appeared in the Policy Direction Backgrounder, as opposed to the more moderate language found in the actual draft Order.

There seemed to be less attention on the Context Backgrounder, and as has become usual, that is where I like to focus.

I have talked about a theme of balance that I think continues from Minister Navdeep Bains era 5 years ago, balancing Quality, Coverage And Affordable Prices. A few weeks ago, I observed, “In its rejection of an appeal on the CRTC’s Review of Wireless Services, just last month Cabinet said: “the Governor in Council considers that the Commission’s decision appropriately balances investment incentives to build and upgrade networks, and sustainable competition and the availability of affordable mobile wireless prices for consumers”.”

Nearly two years ago, Minister Bains said Canada’s Future Depends on Connectivity. Generally, last week’s telecom policy announcement promises a framework that continues to balance consumer interests, including the incentives for service providers to make investments that deliver quality services, available to all Canadians.

Policy consistency is important. The context backgrounder leads with details of how these policies have delivered benefits for Canadian consumers:

Canada has benefited from very high investment levels over time, with the private sector investing $11.4 billion in 2020. Canada has consistently been above the Organisation for Economic Co-operation and Development (OECD) average. For example, in Canada the share of telecommunications revenues invested in capital expenditures over time was 30-50% above the OECD average. This has led to high quality telecommunications networks. For example, according to Ookla’s March 2022 Global SpeedTest, Canada ranked 16th out of 142 countries for median mobile speeds, ahead of all members of the G7, and 17th out of 182 countries for median fixed broadband speeds ahead of all members of the G7, except the USA and Japan.

When it comes to the household availability of full fibre networks, in 2020 the household coverage in Canada (49%) was ahead of the US (42%), Australia (16%), UK (18%), Germany (11%), and Italy (34%) and the EU average of 43%. Similarly, when factoring in cable networks, coverage of the faster speeds of 100 Mbps and 1 Gbps are available to 87% and 76% of homes compared to 76% and 51% in European Union countries. Data from OpenSignal shows strong speeds for new Fifth generation (5G) services with Canada ranking 4th in 2021, strong historical coverage of 4G services, and for more specialized application metrics Canadian operators were not among global leaders but above the sample average. Fibre and new 5G services continue to roll out and ongoing investments will ensure Canadians benefit from these and future technologies as they are introduced and deployed.

The subsequent paragraphs, talking about rural service gaps, demonstrate an understanding and appreciation of the challenging aspects of business cases to build in parts of Canada.

The background document provides a market overview and helps to understand the context in which policies are being formed, “promoting more competition, universal access and a more consumer-oriented telecommunications sector in Canada.”

Minister Champagne said “We recognize the important balance that must be achieved between the need to invest in our networks and the need to promote continued competition and affordability.”

This reference to balance, coupled with the Policy Direction’s requirement for predictability, provide important messages of policy consistency.

Have we seen the end of Calvinball in Canadian telecom regulation?

Value, affordability and investment

I have frequently written about the regulatory policy tension in balancing quality, coverage and price for telecommunications services. These were key attributes at the foundation of the Canadian government’s policy statements over the past 5 or so years.

There has been an explicit recognition in Canadian policy that the public interest is multi-dimensional, seeking lower prices, while continuing to provide incentives for investment in new technologies and expanded coverage.

A recent blog post by CWTA uses a similar trilogy of terms: value; affordability; and, investment. “Canada’s wireless industry delivering greater value, affordability and investment” criticizes the level of attention “given to one-dimensional and misleading price comparison studies that paint an inaccurate picture of telecom prices and affordability in Canada” and concludes with:

Canada’s economic well-being, safety and quality of life depend on high-quality digital infrastructure. Making world-class telecommunications services available to all Canadians at affordable prices remains the focus of our industry.

No one is saying that Canada has the lowest prices in the world, but contrary to what some would have us believe, Canadian telecom prices are not the most expensive in the world and Canada is not an outlier when it comes to prices. Comparing prices to other countries without factoring in differences in average income levels, quality of service, and cost structures produces misleading results. And as I have written recently, price and affordability are not the same.

As someone who pays bills each month, I too would like lower prices, just as I do for housing, gas, water, electricity, milk, chicken, eggs and everything else. But I also want fast mobile broadband when I am in the suburbs and rural parts of the country. That takes a balance of the various factors that make up the public interest, not just looking at price.

In May, I wrote about an Opensignal report indicating “that Canada’s mobile customers put a value on quality, and will migrate between service providers based on their mobile network experience.”

I had a multi-part Twitter thread on that theme:

Prices are declining, consumers get more data included in plans and at far faster speeds. Aided by regulatory certainty, investments are being accelerated by carriers, expanding the reach and coverage of wireline and wireless networks, both fixed and mobile. Advanced technologies, such as 5G and fibre to the home are not just for Canadians in urban centres, but also in rural and remote regions. More Canadians are signing up for mobile and fixed services every month, evidence of people are finding plans that suit their budgets.

As I wrote last week, we need to do more work to understand and develop solutions for the factors that are inhibiting adoption by those Canadians who have access but have not yet subscribed. That is a different challenge from the industry focus on delivering greater value, affordability and investment.

Scroll to Top