Consumer protection or regulatory theatre?

When does consumer protection become regulatory theatre?

I think that’s a question worth asking as the CRTC continues to introduce increasingly prescriptive requirements governing how telecommunications providers communicate with, sell to, and serve their customers.

Each new measure sounds reasonable enough. More disclosures. More notifications. More detailed rules governing customer interactions. More opportunities to complain.

But are consumers actually better off?

Consider the CRTC’s recent decision on broadband speed disclosures. The Commission has effectively defined “typical” Internet speeds as speeds customers should receive “at all times,” while simultaneously recognizing that compensation for slower speeds should depend on the materiality and frequency of the problem.

The result? A regulatory framework that risks encouraging technical disputes over speed-test results, even where customers experience no meaningful degradation in service.

Then there’s the ongoing proceeding examining consumer awareness of the Commission for Complaints for Telecom-television Services (CCTS). The CRTC is considering requirements that would notify customers of their right to complain earlier in the customer-service process.

But where is the evidence that earlier notifications will produce better outcomes?

More referrals to the CCTS won’t necessarily mean more complaints will be resolved, or that consumers are receiving better service. They could simply mean more complaints are being diverted from providers’ own resolution processes.

Meanwhile, the Commission’s proposal to harmonize its four consumer protection codes risks becoming an exercise in regulatory expansion disguised as simplification. Combining existing codes into one document isn’t simplification if the result is more obligations applying to more services. That’s regulatory theatre.

Each of these initiatives carries implementation costs. IT systems to be modified. Employees to be trained. Billing and customer-service processes to be redesigned. Compliance to be monitored and documented.

And for what measurable incremental benefit?

Legal scholars Omri Ben-Shahar and Carl Schneider have examined this phenomenon in their research on the failure of mandated disclosure. Their work explains why such requirements are politically attractive: they create the appearance of consumer protection, while their actual effectiveness often goes unexamined.

It’s easy to mandate another disclosure or notification. It’s much harder to demonstrate that it changes consumer outcomes. That’s regulatory theatre.

The problem is compounded when regulations are considered individually.

The CRTC examines each proposal on its own merits, but who is assessing the cumulative burden of successive consumer protection requirements? Who is measuring whether the combined costs are justified by improvements in consumer welfare?

These aren’t just academic questions.

Telecommunications is a capital-intensive industry. Resources devoted to implementing increasingly elaborate regulatory processes are resources unavailable for other priorities, including improving networks, developing services and enhancing the customer experience.

The timing is striking.

On October 21, the federal government announced a new Cabinet Directive on Regulatory Competitiveness and Red Tape Reduction. Taking effect December 31, it calls for evidence-informed, proportionate and outcome-focused regulation, with greater attention to compliance costs, competitiveness and unnecessary regulatory burden.

The government went so far as to establish a requirement to offset two dollars in regulatory burden costs for every dollar added.

The directive doesn’t automatically apply to CRTC regulatory decisions. But shouldn’t the principles behind it be reflected in the Commission’s approach?

Canada’s 2023 Telecommunications Policy Direction already calls for efficient and proportionate regulation that considers its effects on investment, innovation and competition.

Yet recent proceedings suggest an increasingly prescriptive approach to consumer protection, one in which the existence of a perceived problem too readily becomes justification for another regulatory obligation.

No one is arguing against protecting consumers. Accurate information, fair treatment and effective complaint resolution are legitimate regulatory objectives.

But good intentions don’t establish that a particular intervention is necessary, effective or proportionate.

Consumer protection should be measured by the problems solved, not the obligations imposed.

Otherwise, we risk confusing regulatory activity with regulatory achievement.

And Canadians may end up paying for increasingly elaborate consumer protection rules without receiving much additional protection.

That’s regulatory theatre.
Two big releases

There were two big releases today that impact the telecom sector.

The Competition Tribunal released its decision in a deceptive marketing practices case against Rogers, granting the application brought by the Commissioner of Competition.

By promoting and advertising across an array of marketing channels in Canada as “unlimited” or “infinite” mobile data plans that had a pre-determined and finite amount of high-speed data, after which the speed would be significantly reduced for the remainder of the billing cycle, Rogers’ “unlimited” or “infinite” representations contravened paragraph 74.01(1)(a) of the Act.

The Tribunal has assessed a $15 million penalty. In a statement, Rogers notes that the Commissioner of Competition had sought a penalty of $135M.

We introduced unlimited data plans in 2019 to deliver great value to our customers. These plans eliminated overage fees and gave our customers bill certainty at a time when data use started growing exponentially. These plans are commonplace in the industry and reflected a significant and positive development for consumers and small businesses. We stand behind our advertising and are considering next steps.

The Order is currently very brief since the Tribunal is working with the parties (the Commissioner of Competition and Rogers) to identify confidential or competitively sensitive information that will be redacted from the public version, expected to be released within the next 2 weeks.

The other one of the big releases earlier today was a Telecom Competition Roadmap released by ISED.

As part of a multi-pronged approach to augment competition, affordability, and transparency for consumers, Innovation, Science and Economic Development Canada is publishing this Telecom Competition Roadmap that outlines a broad range of actions that are being taken over 2026–2027 that each target specific areas for improvement. This is the first time a comprehensive approach is being taken to this issue.

I’ll have more to say about both these releases in the coming weeks.

Did Canada accidentally regulate away telecom investment?

At what point does a policy framework designed to lower prices undermine the telecom investment upon which it ultimately depends? Has Canada crossed that line?

I continue to ask such questions in light of data that continues to show a sharp decline in capital investment by Canadian telecommunications providers, as well as the recent GSMA report (which was the subject of a Telecom Trends post last week).

For years, Canadian telecom policy has been guided by an objective to make communications services more affordable. By many measures, regulators and policymakers have succeeded. Wireless prices are down, competition has intensified, consumers enjoy more choice.

Affordability is only one measure of success. Nearly a decade ago, I wrote about the need to balance “quality, coverage, and price.”

Telecommunications is a capital-intensive industry. Networks don’t improve on their own. Networks don’t expand on their own. Networks are built with telecom investment.

Expanding fibre coverage, deploying 5G, increasing capacity, strengthening resilience, and building next-generation networks all require billions of dollars of ongoing investment. Capital spending is how we pay for “quality”, and “coverage” in the telecom policy balancing act.

That is why the pattern of declining telecom investment should be raising alarm bells.

The CRTC’s own data shows that capital investment has been falling. The question is “why”.

To be sure, regulation is not the only factor. Interest rates, economic uncertainty, market maturity, the completion of major fibre and 5G buildouts, and broader business conditions all impact investment decisions. But, it would be surprising if regulatory policy played no role.

Over the past several years, governments and regulators have consistently prioritized lower prices and expanded wholesale access to existing networks. Those objectives are understandable and politically popular. Yet policies that make it easier for competitors to use infrastructure built by others can also reduce the incentives for facilities-based investment.

Investors pay close attention to those signals from government policy makers and regulators. If expected returns decline, investment tends to decline as well.

This creates an uncomfortable paradox. Those policies intended to help consumers today may inadvertently weaken those incentives needed to build the networks upon which consumers will depend tomorrow.

The consequences may not be immediately felt. Canada continues to benefit from extensive fibre deployment, widespread 5G coverage, and generally high-performing networks. But, the impact will become more apparent over time.

The consequences will be seen in slower upgrades, delayed rural expansion, lower network resilience, and diminished competitiveness in the years ahead. When demand for connectivity continues to grow, driven by cloud computing, streaming, artificial intelligence, and connected devices, sustained declines in investment should not be dismissed as a footnote to the Communications Monitoring Reports.

Too often, investment incentives and disincentives disappear from the policy conversation, or are paid lip service.

At last week’s Canadian Chapter of the International Institute of Communication’s annual conference, the CRTC Chair said:

The infrastructure matters. The rules governing access and competition matter. But ultimately, what matters is whether the system works — whether it connects Canadians, supports businesses and communities, and delivers reliable, affordable services that people can depend on.

The CRTC will continue to do its part: listening to Canadians and industry, making evidence-based decisions, and assessing whether those decisions are achieving their intended results.

The challenge is not to choose between strong networks and strong consumer outcomes. It is to create the conditions for both.

Unfortunately, the CRTC has not responded to a number of years of evidence demonstrating sharp declines in telecom investment.

Price reductions generate headlines; reductions in telecom investment rarely does, despite its role as the foundation upon which future affordability, innovation, and network performance ultimately depend.

Canadians deserve affordable telecommunications services. That should never be in dispute. But, if capital spending continues to fall, policymakers may need to ask whether their dogged pursuit of lower prices has weakened the incentives for telecom investment that made Canada’s world-class networks possible in the first place.

Competition can be mandated. Investment cannot.

Canada’s mobile economy

A new report was released this morning by GSMA examining Canada’s mobile economy, suggesting the telecommunications landscape in Canada has reached a critical juncture. “The Mobile Economy Canada 2026” is ostensibly a study of Canada’s wireless sector. The report supports themes frequently discussed on these pages: productivity, competitiveness and Canada’s place in an AI-driven global economy.

With digital infrastructure increasingly viewed as a strategic economic asset, the continued evolution of mobile technologies will be critical to strengthen Canada’s innovation ecosystem, supporting industrial modernisation and enhancing the country’s long-term global competitiveness. However, sustaining that trajectory, depends on investment conditions, which have become more demanding as the market has matured.

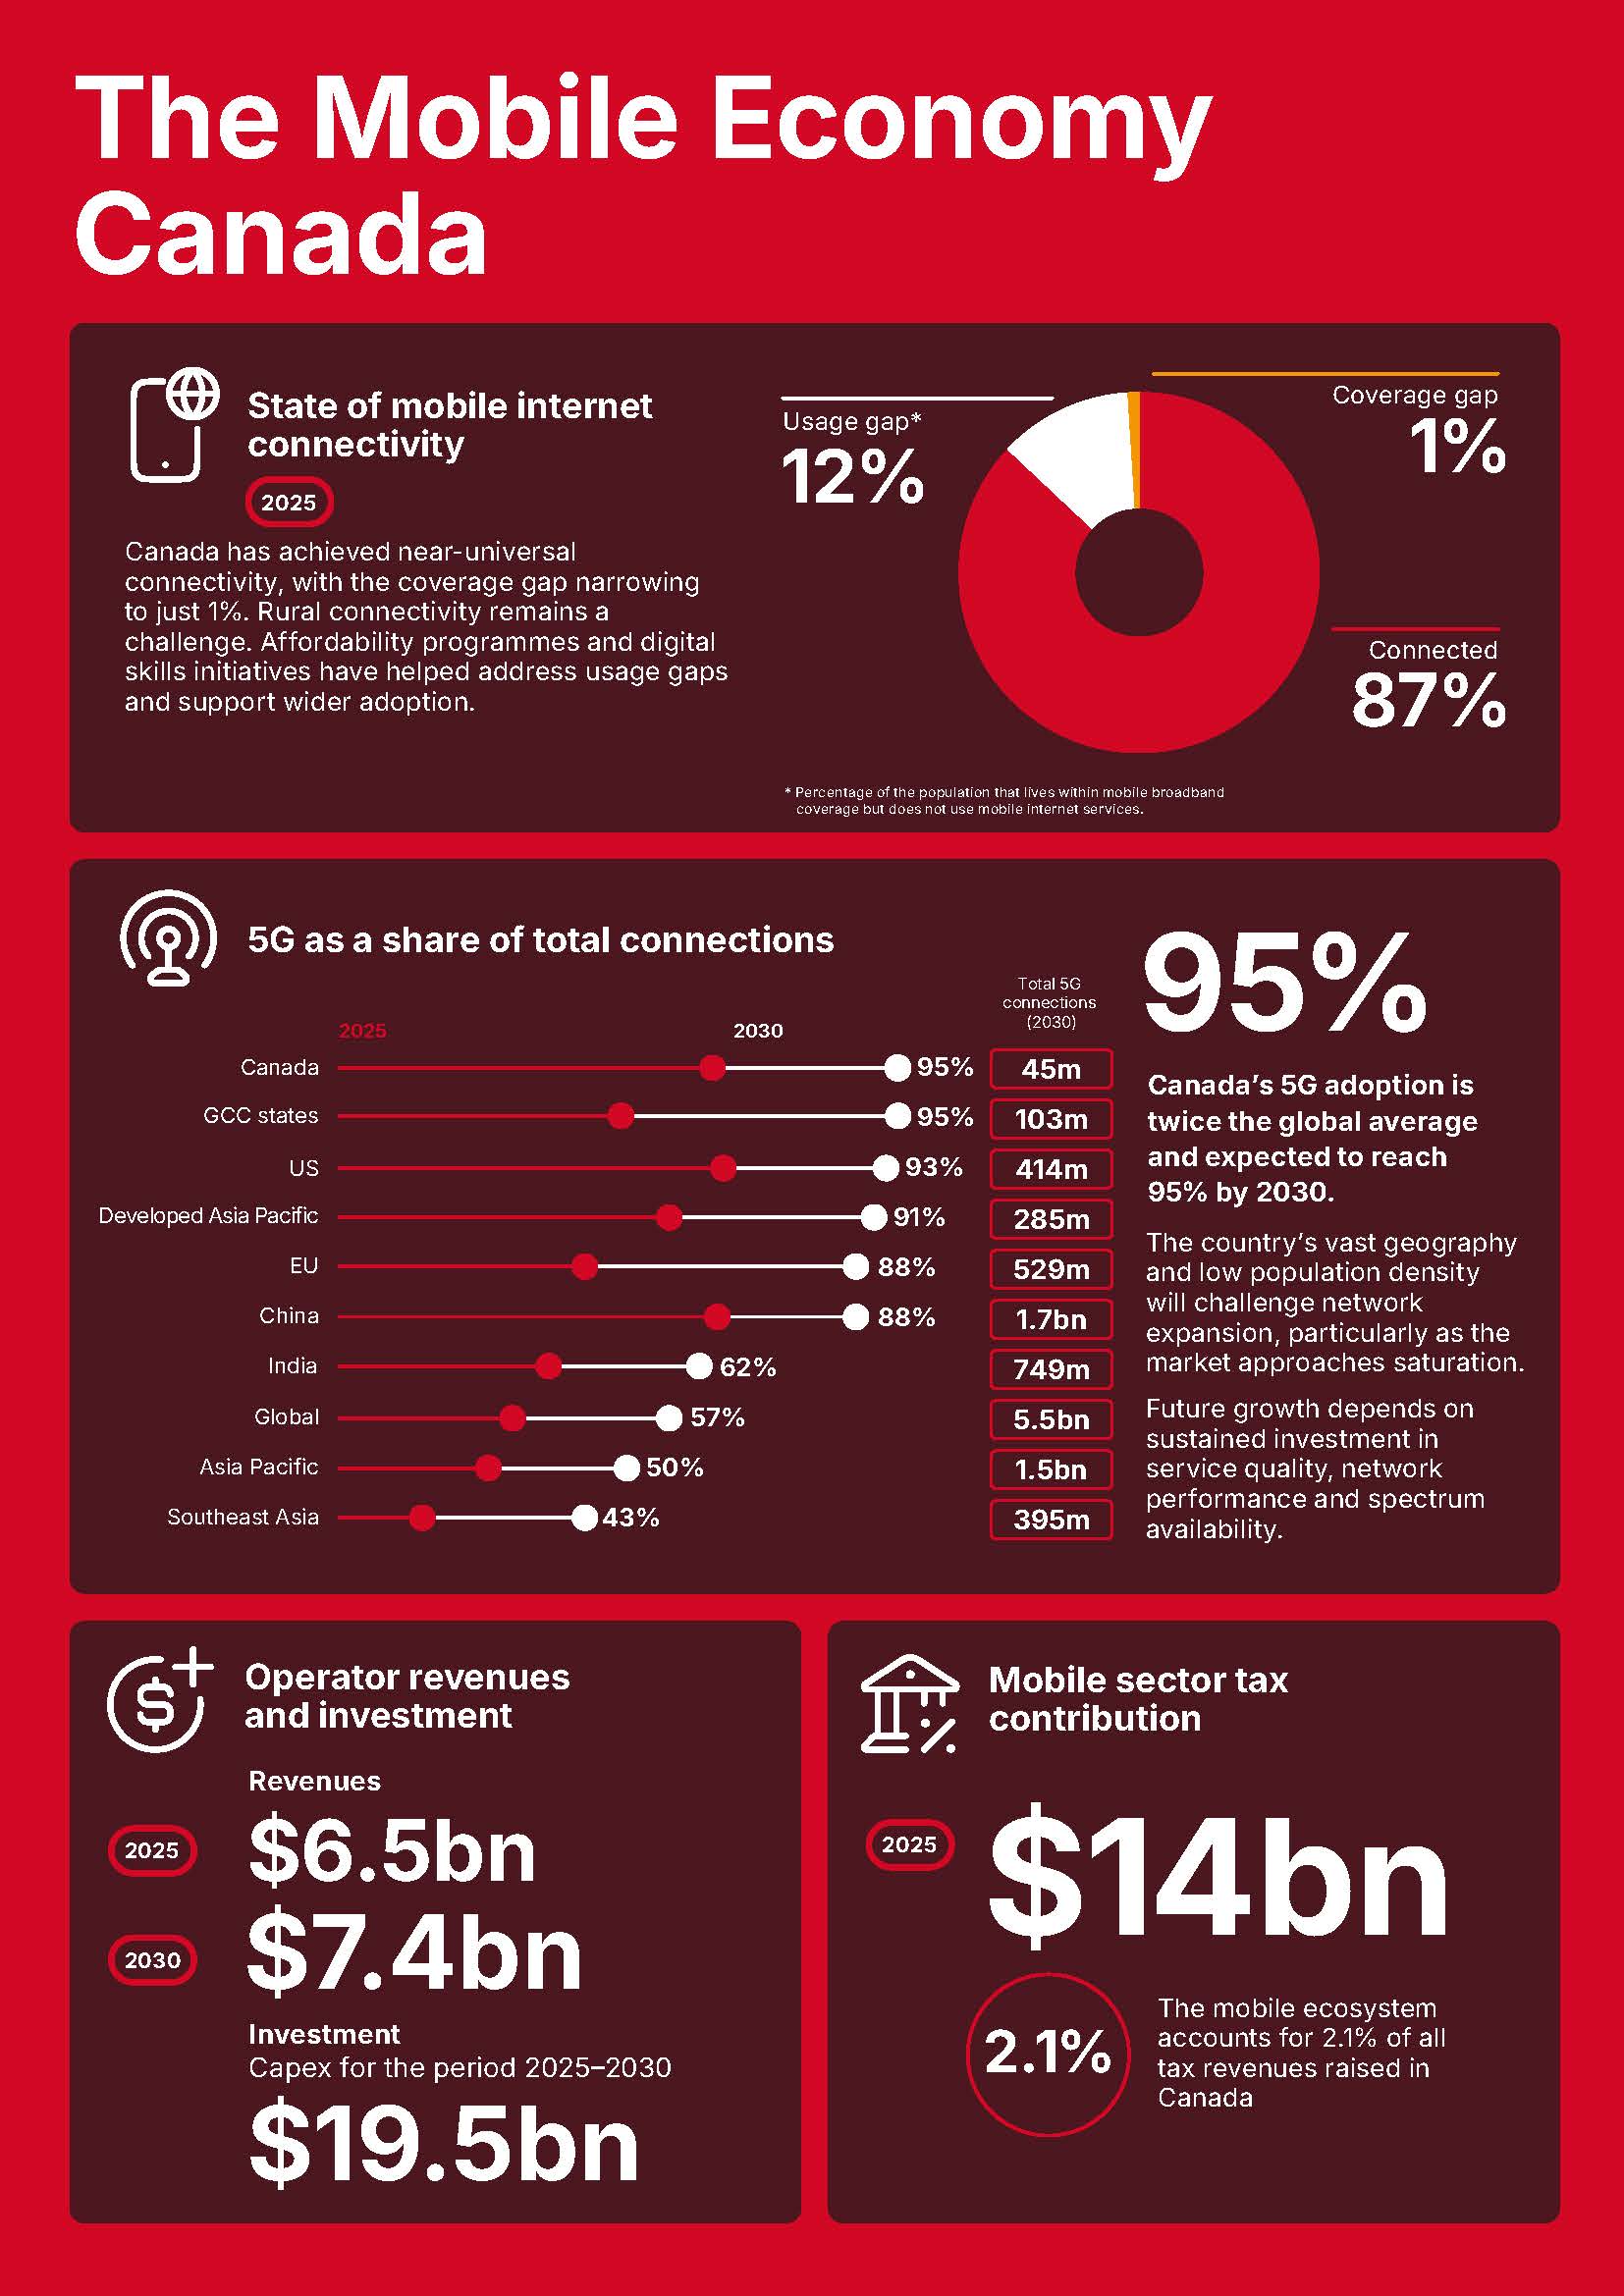
The headline numbers in the report are impressive. Mobile technologies generated US$120 billion in economic value in 2025, equivalent to 5.4% of GDP, while supporting almost 200,000 jobs and contributing US$14 billion in tax revenues. By 2030, GSMA forecasts that contribution will rise to US$170 billion.

An infographic in the report highlights that 99% of Canadians live within mobile broadband coverage and 7/8 of us make use of that connectivity. Canada’s rate of 5G adoption is twice the global average.

But in my view, the kernel of the GSMA report isn’t found in looking at today’s release of a report based on yesterday’s numbers. As you might expect, I want to focus on tomorrow’s risks.

As I complain frequently, Canadian telecom policy has been dominated by affordability and competition objectives – important, but unfortunately short-sighted, with a populist, narrow focus. Eleven months ago, I wrote about a Liberal back-bencher rising in the House of Commons acknowledging the substantial drop in mobile prices being paid by consumers. “Canadians are paying lower prices for cellular services, with a 40% decline in prices over five years.” That wasn’t enough. She continued, “At a time when Canadians are concerned with rising costs and keeping their monthly bills affordable, can the Minister of Industry tell us how the government is working to lower cellphone bills?”

Industry Minister Joly proclaimed in response, “I, and this government, are laser-focused on making sure that we bring down costs in the telecom sector… We also said we would be hawkish on competition. We will do more in this budget to increase competition and make sure that we reform our telecommunications sector.”

GSMA argues that this framework was developed when mobile was a high-growth industry. Today, the market is more mature, revenue growth is slowing, and operators continue to face mounting obligations to fund 5G Standalone networks, AI infrastructure, cybersecurity, network resilience and future spectrum acquisitions.

The report advances a theme that my readers will recognize immediately: investment matters.

That theme echoes several discussions we’ve had over the past few years about the growing tension between consumer affordability and infrastructure investment. GSMA notes that Canada scores exceptionally well on wireless affordability while achieving mid-tier rankings on network performance measures, warning against policies that unintentionally undermine future investment incentives.

The 5G story is similarly nuanced. Canada has achieved more than 94% population coverage and reached one of the highest levels of 5G adoption globally, with nearly two-thirds of mobile connections already on 5G. Yet Canada ranks only 21st on the GSMA 5G Connectivity Index, highlighting a gap between broad coverage and leadership in advanced capabilities such as 5G Standalone, network slicing and enterprise applications.

Perhaps the most interesting section is found when the report focuses on AI.

GSMA sees telecom carriers becoming central players in Canada’s emerging sovereign AI ecosystem. Bell’s AI Fabric initiative, Telus’ Sovereign AI Factory, and operator investments in fibre, data centres and cloud infrastructure are presented as evidence that telecommunications networks are evolving from communications platforms into foundational AI infrastructure. At the same time, GSMA notes:

Canada faces structural constraints that could limit its AI ambitions. The most significant is the scale of its compute and data-centre infrastructure. As of September 2025, Canada had around 1.4 GW of operational datacentre capacity, versus more than 40 GW in the US.

Further, as I have written, AI cannot scale without connectivity. Every AI inference, every cloud workload and every edge computing application ultimately rides over robust communications networks. The GSMA report identifies mobile networks as a critical enabling layer for Canada’s AI ambitions.

The cybersecurity chapter is also worth reviewing. New legislation, mandatory outage reporting and growing concerns about infrastructure theft and cyberattacks are creating additional operational and financial pressures for operators. GSMA observes that resilience is more than an optional network enhancement. It is becoming a statutory obligation. How does this get funded in today’s regulatory and policy environment?

None of this means policymakers should abandon affordability objectives. Rather, the report serves as a reminder that affordability, network quality, digital sovereignty and economic growth are interconnected. Weak investment eventually translates into weaker networks, slower innovation and diminished competitiveness.

The GSMA report, The Mobile Economy Canada 2026, provides a reframing of telecommunications as something more than a consumer service. Wireless networks are a part of our national economic infrastructure, underpinning productivity, AI adoption, public safety and digital inclusion.

As Canada prepares for future releases of spectrum, AI investments, and eventually the transition toward 6G, a central question is whether the policy environment will create the investment climate necessary to sustain it.

The GSMA report can be viewed as a call for policymakers to shift from an affordability-first framework toward an improved balance of competition, consumer interests and long-term infrastructure investment – in short, a return to a more balanced approach for Canada’s telecom policy framework.

[Le rapport, “L’économie du mobile au Canada 2026”, est aussi disponible en français]

Canada’s Digital Future: Nation-Building or Digital Dependency?

Building Canada's Digital Future in the Carney EraFor decades, Canada’s digital policy has focused on connecting Canadians. That challenge is largely solved. The bigger question now is whether Canada will own its digital future or simply rent it from others.

That is the provocative premise behind Building Canada’s Digital Future in the Carney Era, an upcoming Ivey Business School workshop that brings together leaders from government, industry, academia and civil society to tackle an emerging question: What does digital sovereignty actually look like for Canada?

The timing could not be more important.

Artificial intelligence, quantum computing, cloud infrastructure, cybersecurity, robotics and immersive technologies are becoming foundations of economic and geopolitical power. Countries that control critical digital infrastructure, data assets and AI capabilities could set the rules.

For telecom leaders and policy makers, this should raise uncomfortable questions.

Can Canada credibly pursue sovereign AI without sovereign cloud infrastructure? Are telecom networks merely communications platforms, or have they become strategic national assets? Is spectrum policy simply a regulatory exercise, or is it an industrial policy tool?

The workshop will examine how the Carney government’s broader nation-building agenda intersects with digital policy, investment and infrastructure development. Topics include future spectrum policy, trusted cloud services, digital infrastructure financing, network resilience, Indigenous connectivity, and the governance frameworks needed to foster innovation while maintaining public trust.

The workshop agenda asks whether Canada can chart a distinct path as a “digital middle power”, balancing openness to global innovation with greater control over critical technologies and infrastructure.

Will policy makers appreciate what is at stake?

We have reached the point where our conversations shouldn’t be about faster networks or lower prices. The Ivey telecom policy workshops elevate the discussion to examine economic security, competitiveness, productivity and national resilience. The next decade will determine whether Canada becomes a builder of strategic digital capabilities or a customer of technologies developed elsewhere.

For anyone involved in telecom, technology or public policy, this is a discussion worth following closely.

Plan to participate in Building Canada’s Digital Future in the Carney Era, December 2, 2026, at the Donald K. Johnson Conference Centre in downtown Toronto. Register here.

Scroll to Top