Paper artifacts of political pandering

I was glancing through Canada’s Broadcast Act and Telecom Act last night – clearly a sign that I lost interest in the Monday Night Football broadcast – and I came across two sections that bear witness to the failures in digital economy leadership by the last government.

Enshrined in legislation in both Acts is a section prohibiting charging a fee for paper bills. From the Broadcast Act:

34.1 No person who carries on a broadcasting undertaking shall charge a subscriber for providing the subscriber with a paper bill.

And the Telecom Act:

27.2 Any person who provides telecommunications services shall not charge a subscriber for providing the subscriber with a paper bill.

I am certain a legal scholar can weigh in on why the two sections are phrased differently. Both sections were enacted at the same time. Why does the Broadcast Act say “No person… shall charge” while the Telecom Act says “Any person… shall not charge”?

This is the stuff of Talmudic debates.

A much more fundamental question is how such clauses could become part of the legislation that governs the provision of communications services in the year 2015. These are sections that were added in 2014, buried in a budget appropriations act, Bill C-39, that was slammed through Parliament, one of many omnibus bills that characterized the last Parliament.

Where was the discussion about the economic impact of such a bill? Any debate on the signals being sent by such legislation? Evidence heard about the adoption rates of electronic billing when there is a fee differential, versus no fee differential? So many more questions that weren’t considered. This legislation wasn’t required to protect disadvantaged groups; in a meeting with the CRTC, the carriers had offered exemptions from charges to every imaginable group, as I described last year.

The paper bill sections of the Telecom Act and Broadcast Act are testaments to the failures in digital economy leadership of the last government.

Tomorrow, November 4, will see the arrival of a new Cabinet, with new leadership for the development of policy to guide the information and communications sectors.

It is time for a fresh start for fact-based policy making. That would be a real change.
How much competition is too much?

Is there such thing as too much competition?

That question is currently in front of the CRTC and the still un-named Federal Cabinet in two separate applications.

CNOC raised the question in the form of a review and vary application to the CRTC challenging the Commission’s rejection of mandated MVNO arrangements. Bell has put the question before Cabinet in its challenge of a CRTC order to mandate access to fibre networks.

In both cases, the question of impact on investment was an issue. The apparent inconsistency in the conclusions reached between wireless and wireline investment was the subject of one of my posts last week.

Usually, the marketplace takes care of this kind of question. But in the heavily regulated world of telecommunications, various government agencies try to act as proxies for the market, not just in Canada, but around the world.

I have written in the past about my experiences with Golan Telecom, a rather maverick mobile operator in Israel. This morning, word comes that Golan is exploring options and may be acquired by Pelephone, one of Israel’s original mobile operators. Reuters writes “Israel wonders if too much competition a bad thing in mobile market” as “concerns grow that cut-throat competition is undermining firms’ ability to invest in infrastructure, leaving Israel trailing other nations despite its reputation as a high-tech leader”.

For wireless and wireline, how much competition is too much?

Can the market decide?

Crowd-sourcing the CMR

To maximize media coverage, the CRTC is trickling pieces of its 2015 Communications Monitoring Report. I think it may be a sneaky way of getting the public to help do proof-reading and submit corrections.

Little slips have made the communications strategy obvious. On October 22, the CRTC Twitter account let slip a little factoid that wasn’t actually published in the excerpt published last week:

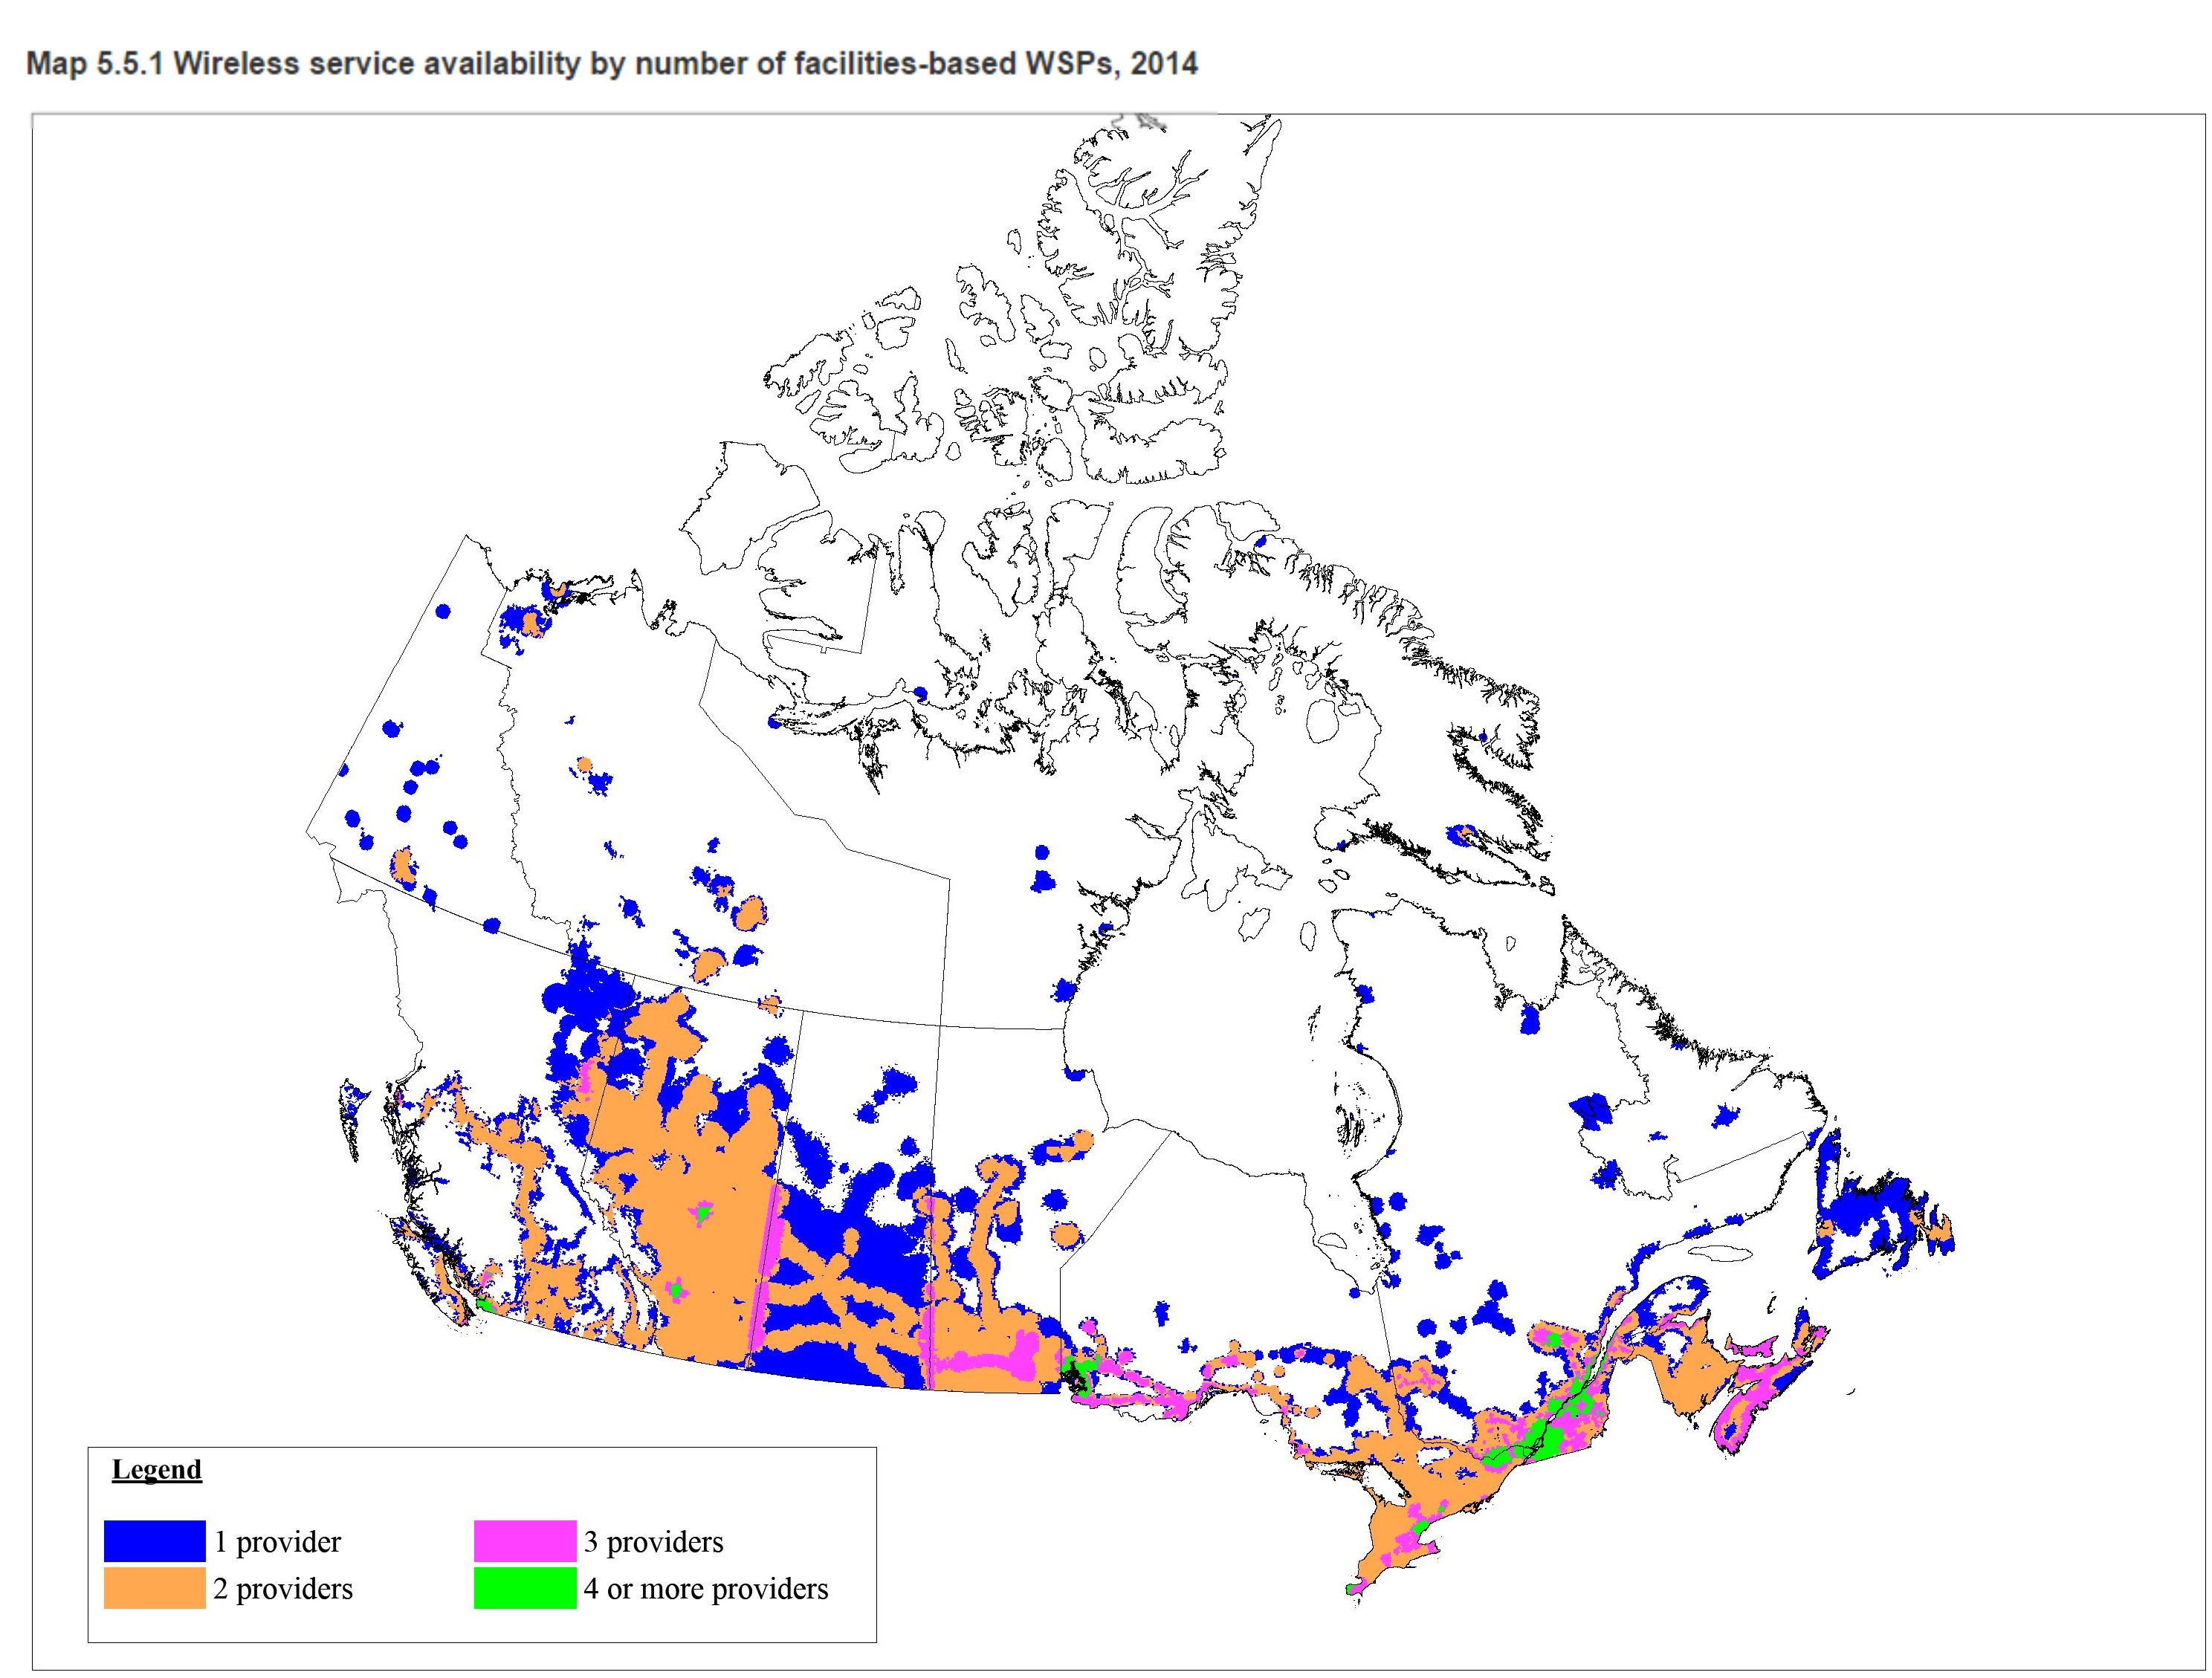
Map 5.5.1 2015 CMRThat figure didn’t actually show up until today in Figure 5.5.8.

In the excerpt of the report released earlier today, the CRTC refers to a mysterious Appendix 9. There is no Appendix 9 in the report. There are no appendices at all. Perhaps they will show up in the next release.

When the Commission finishes teasing us with partial releases, we’ll hopefully see a complete final edition, in the customary full html and pdf formats.

In the meantime, we’re detecting some gaps in the analysis, with a couple glaring errors. Maybe the strategy is to get us to help do the proof-reading.

Map 5.5.1 purports to show “Wireless service availability by number of facilities-based WSPs, 2014”. Now, “WSPs” is a defined term in the report: Wireless service providers. Table 5.5.15 purports to show “Number of different wireless networks, expressed as a percentage of population covered, by province and territory, 2014” and it includes a note that says “In many provinces, facilities-based wireless service providers who own spectrum share the same radio access facilities to offer telecommunications services to the public.”

It appears that Map 5.5.1 is trying to show, in map form, the information that is contained in Table 5.5.15, that is, the number of wireless networks.

It certainly does not reflect the number of facilities based wireless service providers.

A more glaring set of errors can be found in Section 5.3, looking at broadband internet services. In the overview comments in that section, the CRTC confuses coverage with capacity: “While rural Canadians have access to services provided by satellite, capacity limitations restrict practical availability to approximately 1.5% of Canadian households.” No other service is treated that way.

This has a significant impact on Figure 5.3.15, “Broadband, 5 Mbps availability (percentage of households), 2014”. The Commission fails to include satellite in the chart, saying “Satellite service is excluded; however, it would add approximately 1.5% to the availability of 5 Mbps broadband services.” That is a flawed statement, based on the capacity consideration. No other technology is listed showing capacity – they show coverage.

The CRTC appears very confused about how to treat satellite broadband. For example, Figure 5.3.14 purports to show “Broadband availability vs. broadband subscriptions by province/territory, 2014” showing a percentage. The figure includes a note: “These data exclude satellite broadband service for availability, but they are included for subscriptions.”

Huh? So we have a table that could end up showing a higher level of subscriptions than availability? How does that make sense?

Table 5.3.11 has two bold headers for the technologies that are used to provide broadband: “Mobile broadband”; and, “Wireline broadband”. Under which of these two would the subheadings “Fixed wireless” and “Digital satellite” fit? Would you have picked “Wireline broadband”? I might have used “Fixed broadband” as a major heading, instead of “Wireline broadband.”

Maybe the CRTC is trying to crowd-source the editing of this year’s Communications Monitoring Report. The new Minister isn’t being named until next week, November 4.

If you want to help the CRTC get the final report right, add your corrections to this blog post by submitting a comment.


[Update: October 29, 2015] The CRTC has issued the full report [html version or download 10 MB pdf]. The report still refers to the Atlantic provinces as the Maritimes (refer to Canada’s Constitution to understand the difference).

The CRTC invites suggestions from the public to improve the report: “Interested parties are welcome to provide comments for improvements or additions to future editions of the report. You can send your comments to the attention of the Secretary General, CRTC, Ottawa, K1A 0N2.”

Perhaps the CRTC can also consider including an email address in the next edition.

$80 per person

Across all income levels, in 2014, Canadians spent roughly the same amount of money per person on communications – in the order of $80 per person per month for phone, internet and TV.

That was the result of doing a little arithmetic on the data released by the CRTC last week.

Table 2.0.3 Household communications expenditures at a glance, by quintile, 2013
Characteristics First quintile (household income less than $30,668) Second quintile (household income from $30,669 to $51,804) Third quintile (household income from $51,805 to $79,722) Fourth quintile (household income from $79,723 to $121,291) Fifth quintile (household income over $121,292) Average of all quintiles
Average annual income $18,582 $41,105 $64,854 $98,634 $199,702 $84,575
Members per household 1.49 2.11 2.49 2.95 3.34 2.48
Communications expenditures as a percentage of annual income 8.3% 4.9% 3.8% 2.8% 1.7% 2.9%

Sources: Statistics Canada’s Survey of Household Spending

I did a little more analysis on that table, using simple arithmetic to derive the following:

Supplementary analysis
Characteristics First quintile (household income less than $30,668) Second quintile (household income from $30,669 to $51,804) Third quintile (household income from $51,805 to $79,722) Fourth quintile (household income from $79,723 to $121,291) Fifth quintile (household income over $121,292) Average of all quintiles
Average Communications Bill $1,542.31 $2,014.15 $2,464.45 $2,761.75 $3,394.93 $2,452.68
Annual Bill per Person $1,035.10 $954.57 $989.74 $936.19 $1,016.45 $988.98
Monthly Bill per Person $86.26 $79.55 $82.48 $78.02 $84.70 $82.42

One of the factors impacting the higher cost on a per person basis in the lowest income quintile may be the smaller average household size – just 1.49. While mobile services are sold to individuals, other services (TV, home internet, wired phones) are sold to the household. The slightly higher cost of communications on a per person basis in the lower income levels might be attributable to a “single supplement” effect – a higher cost per person due to living alone.

Telecom service provider marketing departments and social service agencies alike need to consider household sizes as they examine ways to help make services more accessible for these lower income quintiles.

Smaller household sizes would also be an explanation for why lower income households have a greater tendency to be wireless only. The CRTC suggested that it may be an issue of affordability:

Yet as Canadians embrace mobile wireless, a more precise picture emerges when examining this trend across income quintiles. For instance, wireless-only households are most prominent among the two lowest income quintiles … This suggests that the rise of mobile-only households does not solely reflect changing preferences but may also be driven by affordability.

It is important to look at the significant differences in size of household across the income quintiles. With small households, affordability may not be the most important factor driving wireless-only choices.

In the case of single member households, at any income level, going “wireless only” is just plain common sense.

Wholesale inconsistency

Is the CRTC sending inconsistent messages?

In my blog post last night, I indicated that the CRTC’s determinations to mandate wholesale access to next generation fibre networks took Bell, and likely the other major wireline carriers, by surprise.

Let’s look at a chronology.

The CRTC had open proceedings examining the wholesale regimes for each of wireless and wireline service in 2015, processes that began in 2013 [see: Wireless notices 2013-685 and 2014-76; and, Wireline notice 2013-551].

On May 5, 2015, the CRTC issued its decision on the wireless file in its Telecom Regulatory Policy CRTC 2015-177. Among the issues being examined was whether the CRTC should mandate access to facilities-based wireless networks by MVNOs – Mobile Virtual Network Operators. Many similar arguments regarding the impact on investment were raised by the wireless carriers as we heard in respect of wireline facilities. It was a key concern of the CRTC on the wireless side, and the following statement is found in the Commission’s summary at the top of the decision:

The Commission’s determinations in this decision will facilitate sustainable competition that provides benefits to Canadians, such as reasonable prices and innovative services, as well as continued innovation and investment in high-quality mobile wireless networks.

But the CRTC reached a very different conclusion on mandated resale on the wireless side from how it ruled for fibre. Despite finding “the barriers to entry into the retail market are very high” and the difficulty of “wireless service providers to obtain wholesale mobile wireless services from other wireless carriers, in particular the national wireless carriers, at reasonable rates, terms, and conditions”, the CRTC rejected mandating resale for wireless.

  1. Investment in wireless network infrastructure by wireless carriers is important to ensure that Canadians have access to mobile wireless networks and services of high quality in all regions of Canada. The new entrants have made and are planning to make significant investments in spectrum and their wireless networks. The Commission considers that mandating wholesale MVNO access at this time would significantly undermine these investments, particularly outside urban core areas.
  2. Accordingly, if the Commission were to mandate GSM-based wholesale MVNO access provided by the national wireless carriers, this permanent network access would likely discourage continued investment by wireless carriers, because they could rely on this access rather than investing in their own mobile wireless network infrastructure.

That was in early May. The wireline decision was still outstanding, but in mid-June, Bell and TELUS made multi-billion dollar announcements for major fibre-to-the-home (FTTH) investments in their largest cities. At the time, many observers wondered if the telephone companies were anticipating a similar approach by the CRTC for wireline.

In July, the CRTC finally released its Telecom Regulatory Policy CRTC 2015-326 with the wireline wholesale policy. It acknowledged that the impact on investment was a consideration in the development of its policy [see paragraph 51]:

Innovation and investment – mandating or not mandating the facility or wholesale service could affect the level of innovation/investment in advanced or emerging networks or services for incumbents, competitors, or both, or impact the associated level of adoption of advanced or emerging services by users of telecommunications services.

The telephone companies warned that mandating access to FTTH access facilities would impact investment decisions, as acknowledged by the CRTC in the decision:

  1. All of the ILECs raised concerns regarding the impact that mandating the provision of FTTP access facilities could have on their investment decisions. For example, the Bell companies argued that the business case for investment in FTTP access facilities was challenging, and would only worsen if the Commission proceeded to mandate the provision of wholesale HSA services over these facilities. Bell Aliant cited its FTTP deployment program in Ontario, which it scaled back in light of unforeseen costs, to demonstrate the fragility of the business case. Moreover, Bell Aliant argued that mandating the provision of FTTP access facilities may reduce or delay future technology upgrades in areas currently served by FTTP, thereby broadly harming consumers.
  2. Similarly, TCC argued that the mandated provision of FTTP access facilities would result in less fibre deployment, and that this would occur not just in lower-density areas, where the already-challenging business case will be eliminated, but more broadly throughout Canada. TCC indicated that if the Commission is not prepared to reject the mandated provision of FTTP access facilities, the negative effects of this regime on investment in next-generation broadband facilities should be attenuated through a moratorium on mandated access to Internet access services at higher speeds.

Similar concerns, but different conclusions. In the case of wireline wholesale, the CRTC shrugged off the impact on investment with a simple statement at the end of a somewhat unrelated paragraph dealing with implementation: “any investment risks associated with mandating the provision of wholesale HSA services over FTTP access facilities can be attenuated by providing the incumbent carriers with a reasonable rate of return.”

Under the Policy Direction, the CRTC is required to take into account the principles of technological and competitive neutrality.

At the bottom of each of the CRTC decisions, there is a section dealing with whether the orders are consistent with the Policy Direction. In particular, the wireline policy says:

  1. Consistent with subparagraph 1(b)(iv) of the Policy Direction, the Commission’s determinations, as they relate to network interconnection arrangements or regimes for access to networks, are technologically and competitively neutral and do not artificially favour either Canadian carriers or resellers. In this regard, the Commission notes that its determinations regarding disaggregated wholesale HSA services apply to all incumbent carriers, and require such services to be provided over any underlying technology, including FTTP access facilities.

The wireless policy has a similar paragraph:

  1. Consistent with subparagraph 1(b)(iv) of the Policy Direction, the Commission considers that its determinations, as they relate to network interconnection arrangements or regimes for access to networks, are technologically and competitively neutral and do not artificially favour either Canadian carriers or resellers.

Perhaps considered independently, the determinations technologically neutral, but are the two policies consistent when considered together? Both proceedings were open at the same time. Did the CRTC ensure that the conclusions of both wireless and wireline wholesale proceedings would be technologically neutral?

Scroll to Top